
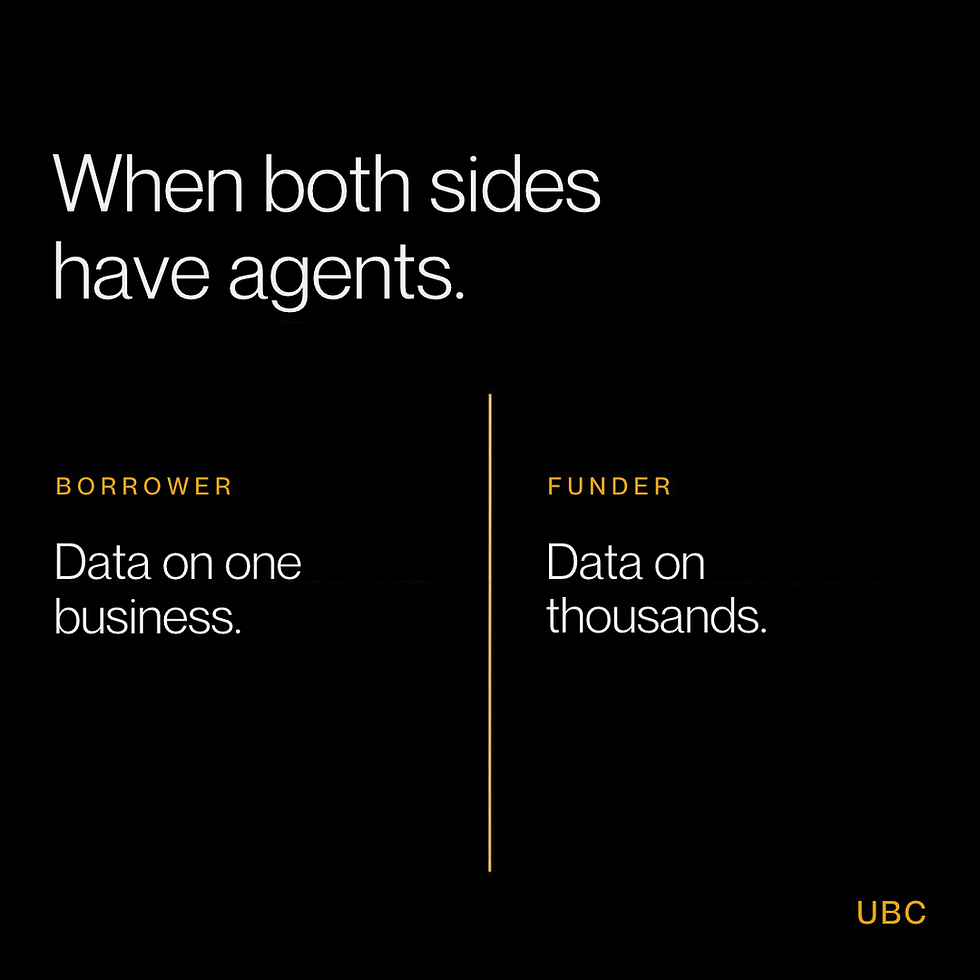
Commentary on AI funding agents has focused almost entirely on the borrower. The premise is straightforward: a small business deploys software that compares funding options, negotiates terms, tracks obligations, and recommends when to refinance or repay. Ultimate Business Capital, a Wyoming specialty finance firm that buys performing commercial receivables, views that premise as incomplete. The more consequential question is what happens when the funder deploys AI funding agents as well.
What AI Funding Agents Promise Borrowers
The borrower-side case has merit. Most small businesses raise capital reactively. Cash tightens, an application goes out, and terms reflect whatever the market offers that week. Once a facility funds, few operators revisit whether the structure still fits the business. An agent that compares term loans, lines of credit, invoice financing, and revenue-based funding against actual cash flow, and that tracks drawdowns, remittances, covenants, and renewal dates, addresses a real gap. For most operators, the constraint has never been opportunity. It has been time and continuous oversight.
Funders Will Deploy AI Funding Agents Too
Capital providers will not stand still. If borrowers use agents to shop and negotiate, funders will use them to underwrite and price. Decision cycles will compress on both sides. In Ultimate Business Capital's view, the information gap between borrower and funder does not close under this model. It shifts toward whoever controls the better data.
Why Data Depth Determines the Advantage
A borrower's agent sees one business: its own bank activity, its own receivables, its own obligations. A funder's agent sees deposit patterns, payment behavior, and performance outcomes across thousands of comparable businesses. That cross-sectional view is what allows a funder to distinguish a seasonal dip from early deterioration, or a clean renewal candidate from a business drifting toward default. Ultimate Business Capital's own practice reflects this. The firm independently underwrites every receivable before it buys, reviewing bank activity and payment history rather than relying on reported figures alone. The value of that work comes from comparison, which a single data set cannot supply.
Guardrails for AI Funding Agents
Neither side should grant an agent unchecked authority. Capital decisions create legal obligations, and those obligations require human approval, complete audit trails, defined spending limits, fraud controls, and a named person accountable for each outcome. An agent can prepare a capital decision. It should not own one.
What This Means for Business Owners
For small business owners, the practical implication is less about software and more about records. An agent is only as good as the data it reads. Clean books, consistent deposits, and reconciled statements will matter more, not less, once both sides of the table are automated. Businesses that maintain that discipline now will negotiate from a stronger position later, whether or not an agent sits across from them.

